

“We’re witnessing now the biggest threat to compulsory super, with preservation at its core, in the four decades since it began.”
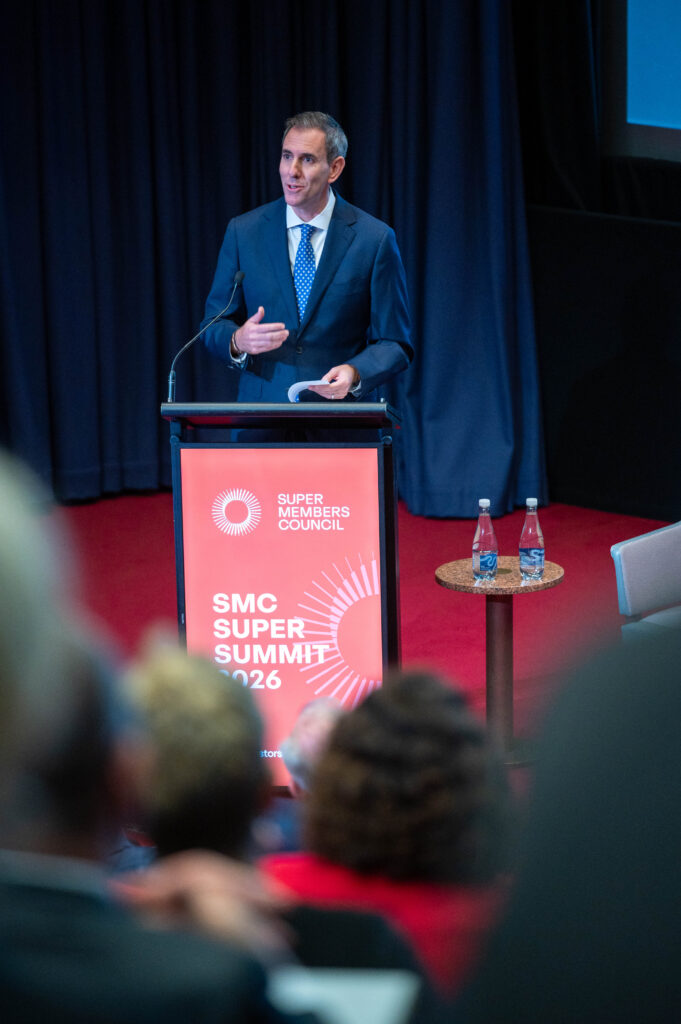
Those were the words Treasurer Jim Chalmers gave to a packed room of super sector leaders at the Super Members Council’s annual summit at Parliament House in Canberra on Wednesday, two days after One Nation announced its election commitment to allow Australians to withdraw 3% of their super for three years to deal with cost of living pressures.
SMC was out quick to release modelling after the announcement showing One Nation’s plan to turn super into an ATM would make battling Australians $25,000 poorer by retirement.
If it became permanent, the policy would wind back the rise in the Super Guarantee rate from 9% to 12% over the past decade – slashing people’s super by $132,000 for an average worker by retirement.
We also know that it will slash investment returns, hit taxpayers with a whopping Age Pension bill, and drive up inflation and interest rates.
Busting open people’s super would also force their super funds to invest differently as their money would need to be invested in short-term liquid options.
SMC’s summit came at an important moment for the super sector and the members they serve. A chance for industry leaders, regulators and parliamentarians of all political tribes to discuss the future of the system and how it best serves Australians, after recent threats to super’s fundamentals.
It was also an opportunity to launch new research examining for the first time how retirees are spending their super and the important impact this is having on jobs and the national economy.
The debate over preservation is often framed around what super can’t be used for today. But increasingly, we’re seeing the enormous benefits that flow when Australians can leave their retirement savings invested for the long term and draw on them when they actually retire.
The research found that in 2026 alone, retirees are expected to spend around $121 billion from their super savings, more than double the amount paid through the Age Pension, supporting more than 485,000 jobs across the Australian economy.
That spending is delivering what could be described as a “double dividend” from super. First, it is helping millions of Australians enjoy a more secure and dignified retirement with higher living standards. Second, that money is flowing straight back into communities, businesses and jobs across the country, from retail stores and hospitality venues to construction sites, manufacturers and professional services firms.
Every time a retiree uses their super to buy groceries, pay household bills, visit family, take a holiday or renovate their home, that spending supports economic activity well beyond their own household. The benefits ripple through local communities and help sustain jobs and wages for working-age Australians.
That adds to the reasons why proposals to raid retirement savings early are so concerning. Preservation isn’t a bureaucratic rule. It’s the foundation that allows savings to compound over decades, providing higher retirement incomes while also generating broader economic benefits for future generations. Weakening preservation risks undermining both sides of that dividend.


